Pensions are your friend, but not your saviour!
Let’s have a look at the benefits of starting a pension and then let’s look at when and how things can go astray due to some wrong assumptions and misunderstandings.
The benefits of commencing a pension are two-fold. Firstly, the income being earned by the assets supporting that pension is deemed to be exempt from income tax. Secondly, the sale of assets supporting the pension are deemed to be exempt from CGT. The caveat we need to put on this is that, unless the members elect to segregate assets supporting pensions from the remaining assets in the fund, the amount to be exempted is not clear and simple. If there are non-pension accounts in the fund during the same financial year, and the pension assets are not segregated from the non-pension assets, then a tax-exempt percentage must be calculated by an actuary to determine what proportion of the earnings and capital gains is eligible to be exempted from tax. This is only required in those ‘transition years’ where the fund is moving from the growth phase to the retirement phase.
Three phases of tax for SMSFs.
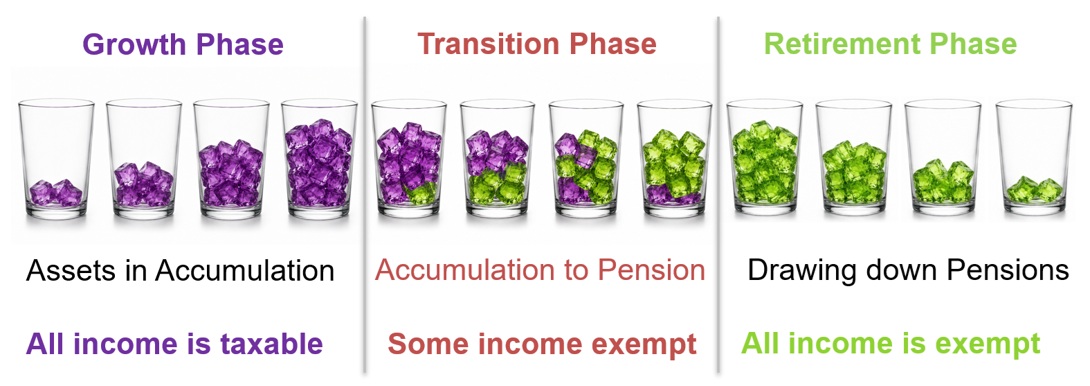
We should all be quite familiar with the growth (accumulation) phase of SMSFs when earnings are taxable and capital gains are fully exposed to CGT. Most of us are also quite aware of the great benefits of making it to retirement (pension) phase where earnings can be exempted from income tax and from CGT. However, it is during the transition phase that things can often go astray, seemingly from over-enthusiasm regarding those great tax benefits.
The transition phase occurs during those years where the fund is not entirely in accumulation phase and not entirely in retirement phase. For some SMSFs, this might be only one Financial Year, and for some it can extend to several financial years, especially with the impact of the Transfer Balance Cap.
During this period of transition, there are often more changes taking place than just the taxation position of the fund. Often during this period members can be shifting their perspective regarding their Investment Strategy, and they can also be looking to offload long-held assets, wanting to capitalise on and lock in the gains that have been made since the purchase of such assets.
To throw in a couple of old cliches here - occasionally the baby gets thrown out with the bathwater, with members, and sometimes their advisors, getting over-excited about the prospect of a pension and putting the cart before the horse. Sometimes with significant (negative) tax implications!
There is a big difference between the full tax exemption available when the whole fund is in pension phase for the financial year and the partial exemption that generally results during a transition year.
An Unfortunate Real-World Example:
Recently we had a two-member fund where one member held roughly 90% of the assets and that member converted to pension phase roughly half-way through the financial year, while the other member remained in accumulation. A property was then sold on the assumption that it would be 90% exempt from CGT (I assume the thinking was that 90% of the fund is now in pension). The pension was then almost entirely drawn down over the next few months leaving just a small pension balance and the accumulation balance of the other member. These members were in for a rude shock when the Actuarial Certificate determined that only around 23% of the earnings were eligible for income tax exemption and consequently only 23% of the capital gain was eligible to be exempted from CGT. The action that they thought would result in only 10% of the gain being subject to CGT actually resulted in 77% of the gain being subject to CGT (not withstanding other, unknown factors impacting the CGT outcome). As you can imagine, this was not a welcome surprise!

Graph of pension and accumulation over the course of the financial year with a property sale soon after the commencement of the pension. The timing of the sale had no bearing on the tax outcome (income tax or CGT).
So where did things go wrong here?
Unfortunately, this is not an isolated incident – just one that was recent and convenient for me to reference. As indicated previously, the enthusiasm and misconception around tax relief from pension commencement appears to be the cause here. Further to that, there appears to be a perception that the tax outcome changes immediately upon commencement of the pension for a member, without consideration of the circumstances of the entire fund.
What do we need to know to fully understand this?
Over the past 22 years when providing simple training sessions around income-tax exemption, I have had a few individuals indicate that they didn’t really care to know how the tax-exempt percentage is calculated, they just wanted the result. That scares me somewhat because the more SMSF professionals that think that way, the more income tax the members are likely to be paying – inappropriately and/or unnecessarily.
Knowing how the calculation of the tax-exempt percentage is performed, and what actions influence the outcome of the calculation, is the first step towards reducing the level of income tax, and CGT, the fund is required to pay. You cannot provide guidance to SMSFs around tax if you don’t know what factors influence the tax outcomes.
How is the tax-exempt percentage calculated?
At it’s simplest form, the tax-exempt percentage is the average pension balance, as a proportion of the average fund balance over the course of the financial year. So, in our example above, the green portion represents the balance in pension and while it peaks at around 90% of the total fund balance, when averaged over the course of the year (which is how it MUST be calculated) it represents less than a quarter of the total fund balance. So, in this situation, it didn’t matter when the property was sold, the tax-exempt percentage would be the same.
How might things have been different?
When the unsegregated method is used to determine the income-tax exemption for the fund, then the timing of a CGT event, and the timing of the receipt of income, has no bearing on the tax outcome. The tax-exempt percentage is applied to all earnings and all capital gains throughout the financial year. If there is no period during the year where the whole fund is in pension phase, then the unsegregated method must be used across the entire financial year.
However, if the whole of the fund had been in pension phase at the time of the sale, assuming the fund was eligible to use the segregated method, then if the segregated method is chosen, a Deemed Segregated Period (DSP) would have been in place, and the timing of the sale becomes significant.
How do the members access full exemption?
To make the most of the benefits of being in pension phase, there are two obvious approaches and one less frequently used approach.
Firstly, waiting until the whole fund is in pension phase for the entire financial year, and realising the capital gain during that year will mean no Actuarial Certificate is required, and all earnings (and capital gains) will be fully exempt using the segregated method. This is the nirvana that the commencement of a pension can sometimes be mistaken for.
Secondly, during the transition phase, if there is a period where the entire fund is in pension phase, and the fund is eligible to use the segregated method, then any income received during that period is fully exempt from income tax, and any capital gains are fully immunised from CGT, if the segregated method is chosen. Even though an Actuarial Certificate is likely to still be required, the calculation and the tax exempt percentage, apply only to the periods that are not full pension – these are known as unsegregated periods. In the example below, a small contribution was made in mid-March which triggered the end of the Deemed Segregated Period and the start of an Unsegregated Period. The tax-exempt percentage shown applies to all income received during the year, other than during the DSP. But importantly, the sale of the asset occurred during the DSP meaning it was fully immunised from CGT.

Graph of pension and accumulation with a Deemed Segregated Period due to the whole fund being in pension phase. The property sale is during the Deemed Segregated Period. The timing of the sale is now significant as the capital gain is immunised against CGT. The tax exempt percentage is less, but this only applies to the unsegregated periods.
Finally, something that seems to be less in use today, but is still as valid and appropriate as ever, members can elect to segregate an asset, or a group of assets, upon commencement of the pension, such that these assets are ‘pension only’ assets. This then means that all income from those assets is exempt from income tax, using the segregated method, and the sale of those assets is immunised from CGT. Again, the fund must be eligible to use the segregated method, and the value of the assets being segregated must be less than the balance of the pensions.
Key Takeaways
• The greater the pension balance during the year, the more income tax you save.
• Starting a pension as early as possible helps boost that tax saving.
• Starting a pension doesn’t automatically immunise capital gains.
• One member’s circumstances do not dictate the tax outcome for the whole fund.
• Don’t assume that starting a pension is going to save lots of tax immediately.
• Feel free to reach out to your Actuarial Certificate provider to check likely outcomes.
• Work closely with those planners/advisors that work with your SMSF clients.
• Encourage the planners/advisors to have more intimate knowledge of income-tax exemption.
• By the time you’re obtaining the Actuarial Certificate it’s all too late, seek guidance first!
If you have any questions about the content of this document please contact Andy on below.
Andy O’Meagher (BSc, GDipEd)
Founder/Director - Act2 Solutions
1800 230 737 andy@act2.com.au
See PDF attached: