SMSF Pension Minimums: Understanding the Latest Ruling
Have you caught up with the latest ruling around failing the pension minimum?
As the recipient of a pension from within an SMSF, the exemption of income tax and CGT is a wonderful benefit. I personally consider this to be the greatest tax benefit of our superannuation system. However, as is so often the case in life, benefits come with some level of responsibility. The key responsibility for a pension recipient is quite a simple one – they are required to draw down at least a certain percentage of their pension balance, depending on their age at 1 July of the financial year. This should not be a huge burden, and one could say that it is a small sacrifice to make to achieve the tax benefits.
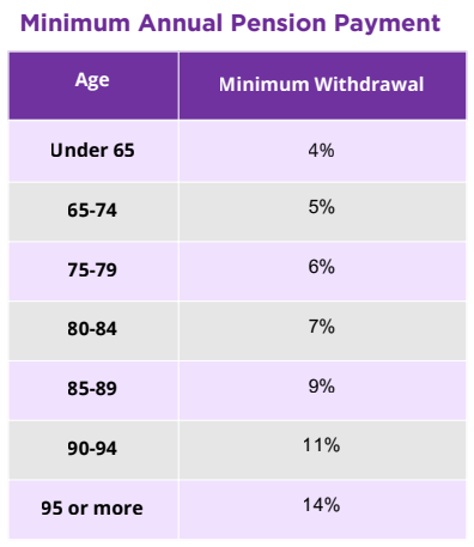
When you examine the pension minimum drawdown table (see below), the intentions are quite evident. In keeping with the overall intention of superannuation, your pension balance should be diminishing such that it is all but depleted near the end of your lifetime. Although there is obviously some allowance here for longevity, which is only appropriate, given that most of us won’t be living into our late 90s. That said, it will be interesting to learn what proportion of Australians are over the age of 95 when the results of our 2026 census are published. The 2020 results indicate that around 28,000 Australians were aged over 95 which is just over one in a thousand or around 0.1% of our population, so not many SMSF pensioners are required to draw down 14% of their balance annually.
Approach and attitude to failing to meet pension minimum over the years.
Since I started in SMSF (At the start of the Cenozoic Era) the approach throughout the SMSF industry to a failure to meet the pension minimum standards has changed significantly. There was a time when ‘catch-up payments’ were made in the following financial year to make up for the shortfall in the previous financial year. The pension would just continue without so much as a ‘speed hump’ and there were no significant consequences. Whilst this may not have been in keeping with best practice, it was a generally accepted industry-wide approach.
Tax Ruling 2013/5 introduced the ruling that a failure to comply with the pension rules deemed that “the trustee is taken not to have been paying a superannuation income stream at any time during the income year in which the requirements are not met.” This resulted in the pension having to be commuted, effective 1 July of the financial year that the minimum failed to be met, but the pension ‘automatically recommenced’ on 1 July of the following financial year due to the ruling wording “If the requirements are again met in the following year this results in the commencement of a new superannuation income stream.” I think it’s fair to say that we can see their intentions here are that it should have been a ‘new income stream’ rather than a continuation or recommencement of the previous one, but I suspect the wider SMSF industry wasn’t particularly consistent with this approach.
So the punishment at this point was that the proportion of earnings associated with the failing pension were no longer exempt in the year that the minimums weren’t met. Earnings were now taxable, and pension benefits were to be treated as lump sum withdrawals from an accumulation account, but the pension was ‘recommenced on 1 July’. This would appear to treat the situation as if the shortfall was immediately identified on 1 July and the new pension was commenced immediately – a situation that is unlikely in practice in the extreme.
We have now progressed to it is not possible to make up the shortfall. If the minimum hasn’t been met, then the pension has failed to meet the minimum pension standards and as such they have failed to comply with the SIS Regulation pension rules that would have been outlined in their pension commencement documents.
So what are the implications of failing to comply with the pension rules now?
Firstly, the pension must be treated as having commuted on 1 July of the financial year that it failed to meet the minimum, along with the TBC account consequences and associated TBAR reporting. Earnings associated with that pension are now taxable (no ECPI for that proportion of the fund) and any benefits paid are to be treated as accumulation lump sums.
No longer does the pension ‘automatically recommence’ as of 1 July of the following financial year. It is recognised that failure to meet the pension minimum is often not discovered until well after the financial year is complete. Most often this occurs when preparing the financial returns for the SMSF and can be several months after the end of the financial year. This is the earliest that the new pension can be commenced, on the date that the shortfall has been identified.
This then requires a ‘conscious’ decision by the member to commute the failed pension (effective 1 July of the year the minimum was not met) and to commence a new pension – no earlier than the date the shortfall was identified. Revaluation of assets at that date is required, as well as calculation of the tax-free and taxable components of the new pension. This new pension must be reported on TBAR.

So now, rather than just losing one financial year of income-tax exemption, the member loses one year and the period up to the date the shortfall is realised. This can be expensive in terms of income tax payable, that could/should have been exempted.
Exceptions / relief when a shortfall occurs.
There are a couple of ways that the pension might be permitted to continue in the event of a shortfall in pension payments.
Once only self-assessment
If the SMSF has never made use of this self-assessment previously, there is a one-off opportunity to make use of this relief but there are strict guidelines around this:
• The underpayment must not be more than 1/12 of the pension minimum.
◦ The underpayment must be as a result of an honest mistake, or outside the member’s control.
• A catch-up payment must be made within 28 days of becoming aware of the shortfall.
• The catch-up payment must be treated as having been made in the prior financial year.
◦ i.e. it cannot count towards meeting the minimum of the year it is made
• This needs to be documented to acknowledge the fund has applied this ruling (called the Commissioner’s Powers of General Administration) for the pension to continue operating.
◦ This should include
⁃ Reasons for failing to meet the minimum.
⁃ That ECPI entitlement was in place if not for the shortfall.
⁃ That the catch-up payment was made as soon as practicable.
⁃ That all other requirements have been met to satisfy the pension minimum.
⁃ Steps taken to prevent this from happening again in the future.
This is a per SMSF situation, not per member. Once the fund has used this approach, it is not able to use it again.
Application for the Commissioner’s Discretion
If the above is not applicable to the circumstances of the fund (i.e. it was not a small underpayment, or if the self assessment has been used by the fund previously) the fund can request in writing to the ATO Commissioner for application of their discretion to allow the pension to continue. All details pertaining to the pension minimum not being met must be provided in the application and these are outlined on the ATO website. This discretion is applied on a case by case basis.
I would issue a cautionary note here. Given the time these rulings often take, and the clearly outlined obligations in TR 2013/5, trustees should consider the most likely outcome from this approach and weigh it up against the amount of tax being paid. Additionally, there is not an option here to ‘hedge your bets’ by commencing a new pension while waiting for the commissioner to allow the previous one to continue. Trustees must consider how many additional months of taxable income they’re likely to suffer whilst awaiting the decision.
Sometimes it’s best to accept your losses and start again.
Shirley Schaefer (Director BDO Audit Pty Ltd) indicated at the SMSF Association Audit Day 2026 that there is a higher burden on auditors to pick up on those who are still operating under the assumption that the old rules are still in place, and auditors will need to verify the ‘conscious commencement’ of the new pensions.
It is reasonable to assume that there will be many who will have failed to pick up on the change of circumstances, given that until recently, we still had some clients thinking they could just make up the shortfall in the subsequent financial year, without any consideration of self-assessment or other consequences. Other than in the self assessment situation (see above) catch-up payments haven’t been permitted since the original release of TR 2013/5 more than a decade ago.
In short, it is best to ensure that SMSF pension members have a full understanding of their obligations as pension recipients, and they are made aware of the potential loss of income-tax exemption (or perhaps best put as additional income tax payable) that can extend well beyond one financial year.
For more information, see the ATO website, specifically:
Income stream (pension) rules and payments | Australian Taxation Office, and
Exception to minimum pension payment requirements | Australian Taxation Office
Andy O’Meagher (BSc, GDipEd)
Founder/Director - Act2 Solutions
1800 230 737 andy@act2.com.au
See PDF attached: